

Hey Girlies,
Emily here. I’m currently looking at a real-life snowglobe out my window, and I hope some of this mid-December magic is finding its way to you!
This past weekend, I attended a “salon,” a social gathering centered around discussion — of art, literature, science, politics and more.
As the snow came down outside, about 15 of us — spanning at least three generations — gathered in the local bookshop for a meal and discussion. And let me tell you, it was just as heartwarming as it sounds.
The discussion began by touching on the assigned reading (Wendell Berry) and quickly drew parallels to the growing pains of the small, tight-knit village I just moved to. A few local businesses are facing an uncertain future, and everyone in attendance wanted to know what they could do to help.
One major point arose multiple times throughout the evening: The importance not only of helping your community, but the importance of asking for help. Jokes were made about the Midwestern tendency to keep problems to yourself, figure it out, and be completely independent.
But we all know nothing good happens that way.
I bring up this conversation because it’s so often the same with money. When facing a financial challenge, we tend to close our mouths, keep it to ourselves, and commit to figuring it out alone. Or worse — we continue along pretending everything’s okay when it’s not.
But all that changes when you let yourself ask for and receive help. Not only does it take a huge weight off your shoulders, but support comes flooding in (this is exactly what happened during the salon).
This is precisely what we want to do with The Finance Girlies — create a judgment-free space for candid conversation and let you know you aren’t alone in your money worries.
This year’s been heavy for a lot of people, so if you’re white-knuckling your finances, let this be your permission to ask for help:
Talk with a friend
Hire a (reputable) financial coach
Pay for hourly financial advising
Seek out financial assistance
Ask us to share our favorite resources
You don’t have to have your money figured out. You don’t have to understand it all alone. And you definitely don’t have to keep quiet about the parts that scare you or confuse you or feel too messy to say out loud.
Turns out, some of the best conversations happen when we stop pretending everything’s fine.
On the pod 🎧
If you’re in the mood for a wait-tell-me-more kind of episode, buckle up. This week on the show, we’re discussing Health Savings Accounts (HSAs) — an underrated savings tool or retirement secret weapon.
Emily and Cass have both used (and loved!) HSAs for years. They sound dreadfully boring, but they’re actually one of the coolest ways to cover medical expenses if you have a high deductible health plan (which both of us do!).
Case in point: Cass has used her HSA for everything from over-the-counter allergy meds and urgent care visits to new eyeglasses and LASIK when she was ready to kick those glasses to the curb. Emily has been investing the money inside her HSA and using it like an extra retirement account.
Listen in to hear:
Why financial pros call HSAs a “triple tax advantaged” account,
How to know if you’re eligible for an HSA,
How HSAs can double as a savings account or retirement fund,
When in your financial order of operations you should think about opening one,
And how to open one.
If HSAs weren’t on your radar before, we think this episode will pique your interest. 👀
More of a reader? Check out the full episode breakdown on our blog.
🎤 Mic drop moment:
“In the event you do have qualified medical expenses in our dystopian hellscape of a for-profit healthcare marketplace, your money goes in tax-free, grows tax-free and comes out tax-free. It’s like the consolation prize for having the world’s most exploitative system.”
— Kattie Gatti Tassin, Rich Girl Nation
Resource roundup 📚
Health Savings Accounts are one of those financial accounts that have a lot of rules, requirements, limits, and caveats. If this is your first time hearing about them, you’ll probably want another resource. This Bankrate article covers HSAs in-depth and may serve as a helpful companion to this episode.
Did you know there’s no age minimum to join the American Association of Retired Persons (AARP)? Before you ask how I (Emily) know this, yes, I’m a member. And yes, I’m 30. Hear me out: It costs $15 per year and gives you discounts on everything from restaurants to travel to car rentals. It also includes 10 issues of AARP The Magazine, which features solid money advice, lots of tips for the technologically challenged (hi), and an appropriately difficult (AKA easy) crossword puzzle to keep the noggin sharp.
This is the kind of year-end podcast episode we wanted to listen to today, so thank you, Tori Dunlap!
Catchup corner 💬
What we’ve been up to:
E: Exploring the new neighborhood — she pretty 🤩
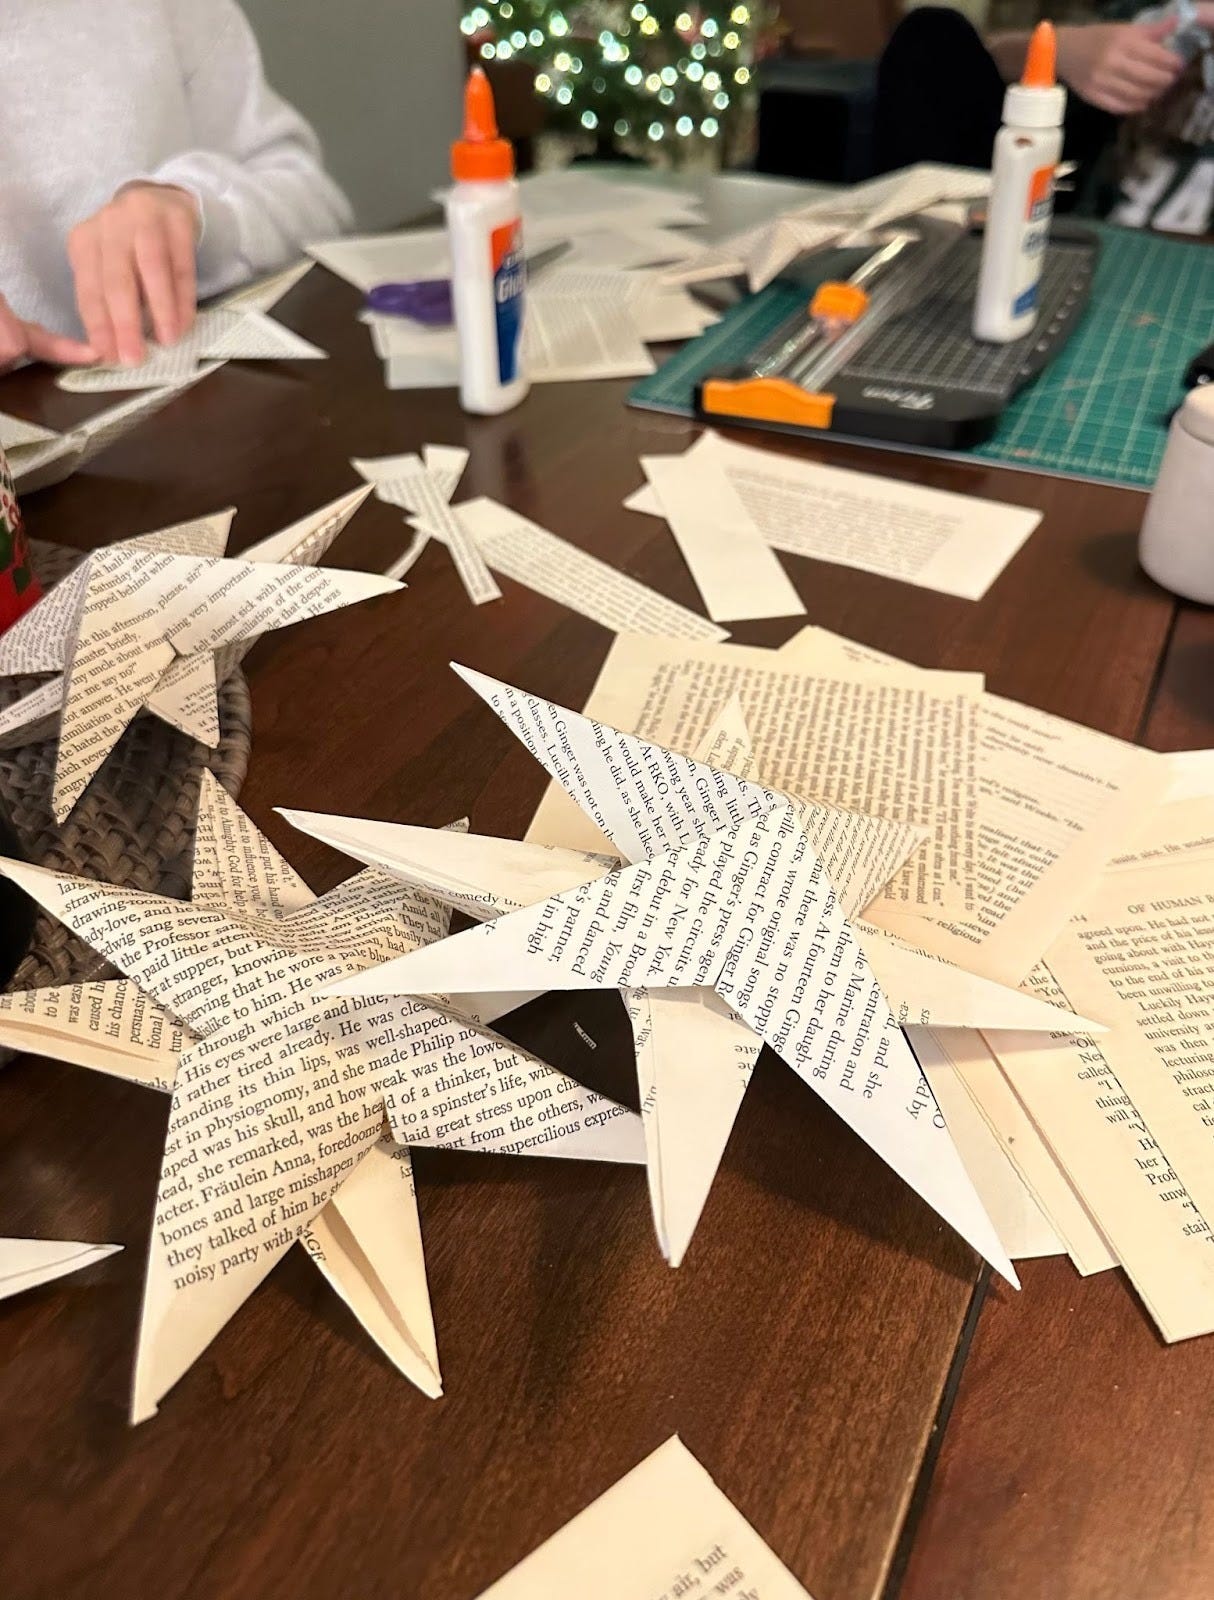
C: CRAFT NIGHTS GALORE! Over the past week alone, I’ve attended craft nights to make paper stars (see below), to make crocheted ornaments, to make salt dough and cinnamon dough ornaments, and tonight I’m attending a craft night to make a holiday wreath. And would you believe… I have even more craft nights lined up before Christmas!
What we’ve been reading/watching/listening to:
E: I usually listen to something while I work — often this boring but helpful focus music. But during the holiday season, I play this instrumental Celtic Christmas music when I’m doing anything other than writing/editing.
C: I have been listening to Lily Allen’s new album on repeat. (Think Beyonce’s Lemonade in terms of tell-all relationship drama. But… British… and about David Harbour, who plays Hopper on Stranger Things.) But beware: You will not be a David Harbour fan after this.
Money moment:
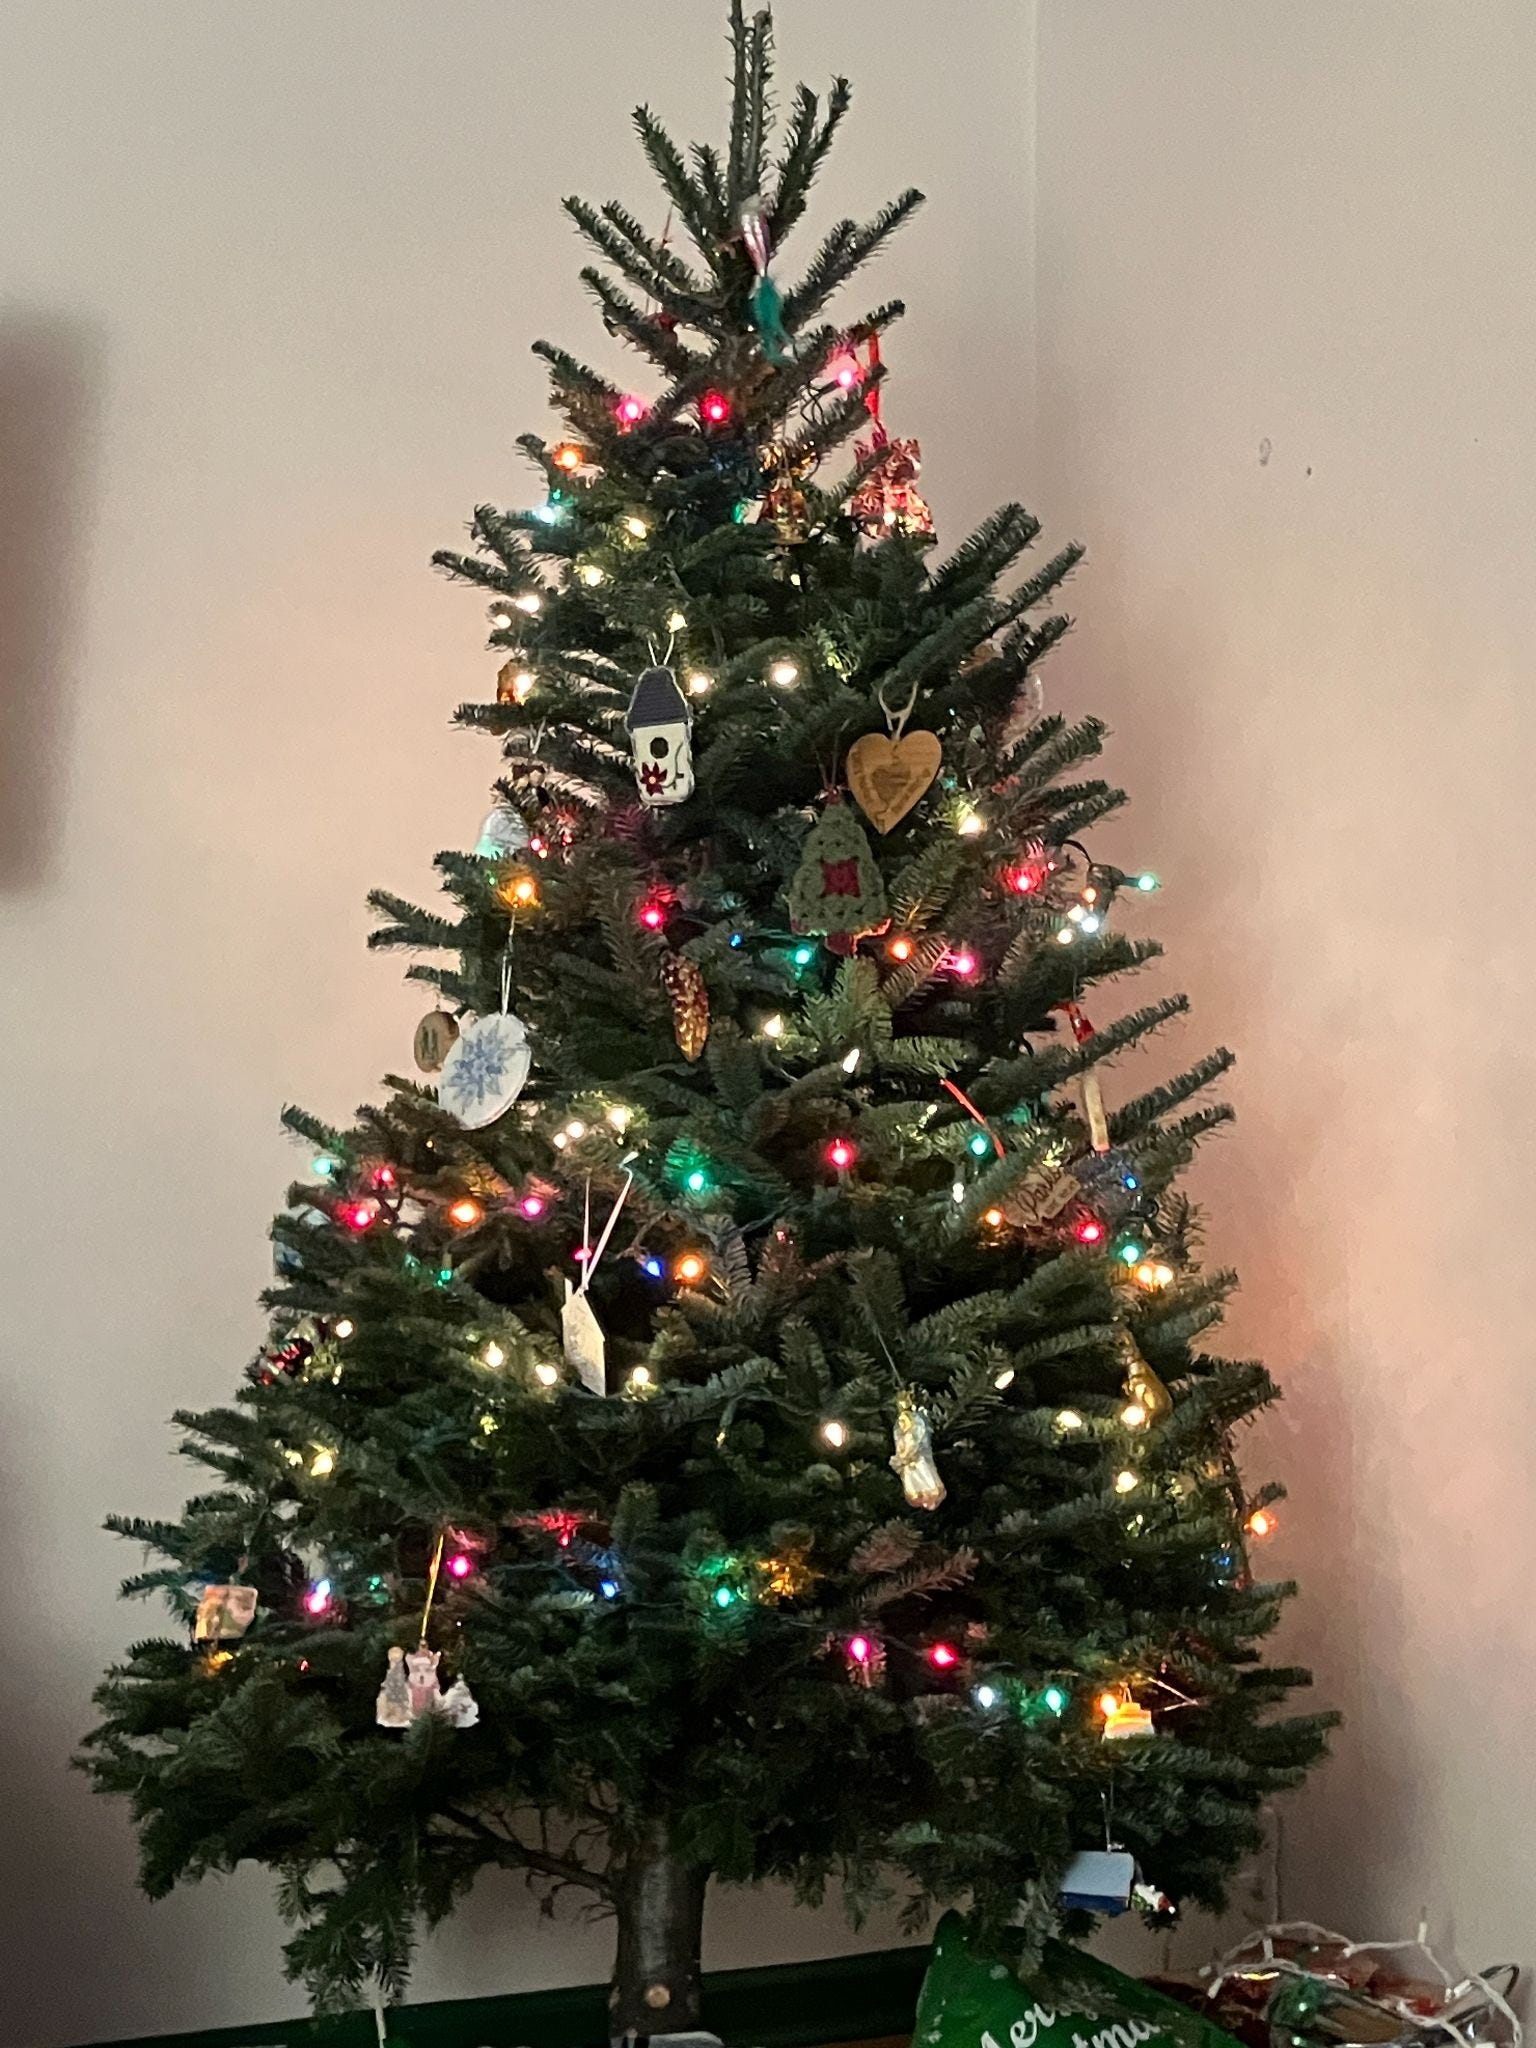
E: Normally, we like to cut down our Christmas tree (ideally in a National Forest, where it costs $5). But this year, moving took up too much time to make the necessary drive and trek. Luckily we discovered a new strategy: Wait to get your tree until the last minute (we got ours December 14th) and get it half off!
C: Last week I attended a paper-star-making craft night at a friend’s house (see photo above). Instead of spending $20+ on fancy scrapbook paper, we went to a local thrift store and picked up some old books for $2 each.
Money tip of the week 💸
Check your HSA eligibility.
Log into your health insurance portal and search for your plan documents. A lot of times, you might see “high-deductible” in the name of your plan, but you can also search for the phrase in your policy docs.
According to the IRS, you’re eligible to open and contribute to an HSA if your health insurance plan if:
You have self-only coverage, and your annual deductible is at least $1,650, and your out-of-pocket max is at least $8,300
You have family coverage, and your annual deductible is at least $8,300, and your annual out-of-pocket maximum is at least $16,600
Love ya, bye!
Emily + Cassidy


